
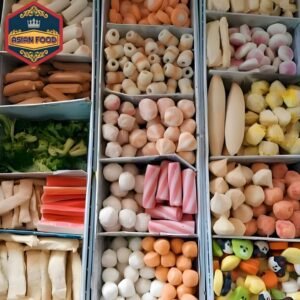

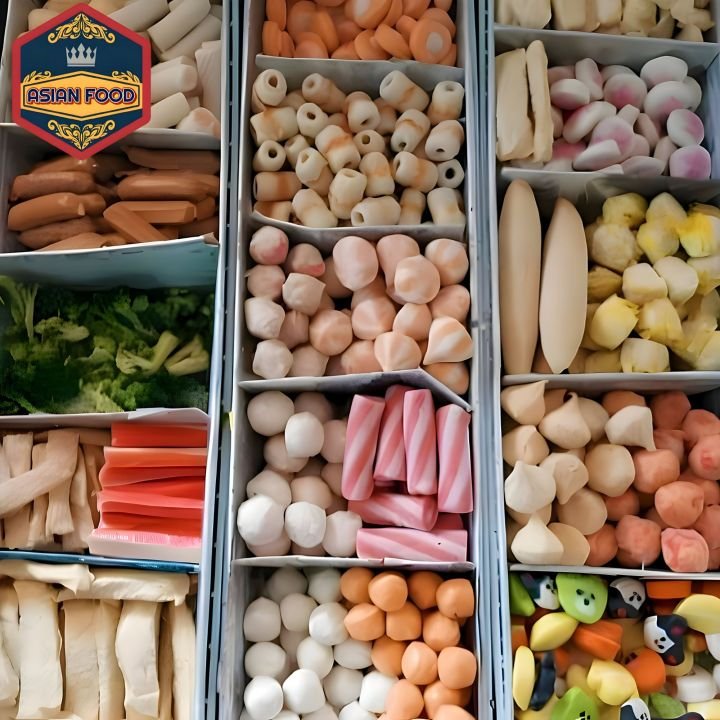
The frozen food business in Southeast Asia is entering a new phase of expansion as consumers increasingly seek food that is convenient, has a longer shelf life and requires less preparation. Future Market Insights estimates the ASEAN frozen food market at about US$11.68 billion in 2025, rising to US$27.42 billion by 2035, representing a compound annual growth rate of about 8.9%. Frozen meat and seafood are the largest category, accounting for about 40% of the market in 2025, while supermarkets and hypermarkets represent roughly 35% of distribution. The growth reflects changing consumption patterns across a region with a large population, rapid urbanization and a growing number of households seeking convenient meal options.
Indonesia is emerging as one of the region’s largest frozen food markets, supported by its population, economic growth and changing consumer habits. Statistics Indonesia, or BPS, estimated the country’s population at 284.67 million in 2025, with 55.65%, or about 158 million people, living on Java. Indonesia’s economy expanded 5.11% in 2025, while nominal gross domestic product reached 23,821.1 trillion rupiah and GDP per capita stood at 83.7 million rupiah, or US$5,083.4. With a consumer base approaching 285 million people and economic growth above 5%, Indonesia offers a scale of potential demand that few other Southeast Asian markets can match.
That scale is reflected in estimates of Indonesia’s frozen food industry. Mordor Intelligence estimates the Indonesian frozen food market at US$3.38 billion in 2025, rising to US$3.61 billion in 2026 and potentially reaching US$5.01 billion by 2031. That represents a CAGR of about 6.78% between 2026 and 2031, adding roughly US$1.4 billion in market value over five years. Compared with an estimated Asia-Pacific frozen food market of US$79.90 billion in 2025, Indonesia would account for about 4.2% of the regional market based on the two estimates.
Indonesia’s demand profile also shows that frozen food is moving beyond its traditional role as a way to preserve food. The ready-to-cook segment accounted for about 61.12% of the Indonesian market in 2025, while ready-to-eat products are projected to expand at a 7.34% CAGR through 2031. Frozen meat and seafood accounted for about 38.07% of the market in 2025, highlighting demand for protein products that can be stored longer and prepared quickly. The shift is creating room for products ranging from nuggets, frozen chicken and seafood to dim sum, potatoes, prepared meals and other protein-based foods to penetrate household consumption.
Indonesia’s advantage lies not only in its population but also in changes in its consumer structure that are increasing demand for convenience foods. BPS data showed that about 68.92% of Indonesians in 2025 belonged to Generation Z, millennials and the younger Post-Gen Z cohort, while the dependency ratio stood at 45.05, meaning there were about 45 people in non-working age groups for every 100 people of working age. About 55.65% of the population lived on Java, creating a concentration of demand that allows food companies to build distribution networks first in areas with high population density. The combination of a young consumer base, urban households and concentrated population centers is increasing the relevance of convenient food products.
Distribution is becoming a critical factor because frozen food requires infrastructure that differs from that of shelf-stable products. In Indonesia, off-trade channels such as supermarkets, hypermarkets and convenience stores accounted for an estimated 81.55% of frozen food sales in 2025, while online retail has emerged as one of the fastest-growing channels. Mordor Intelligence estimates that the off-trade segment could expand at about 6.95% CAGR through 2031, while digital sales are increasingly supported by insulated packaging, gel packs and temperature monitoring. The structure makes investment in freezers, cold storage and temperature-controlled distribution an increasingly important part of the frozen food business model.
Cold chain infrastructure is becoming more strategic because Indonesia has more than 17,000 islands and consumption centers spread from Sumatra to Papua. Within Indonesia’s cold-chain logistics market, storage at temperatures between -18°C and 0°C was estimated to account for 57.35% of the market in 2025, supported particularly by demand for seafood and frozen food. Indonesia’s Ministry of Marine Affairs and Fisheries said in March 2025 that cold storage was important as a buffer stock between periods of high and low production, while a simulation for a 100-ton portable cold-storage facility put investment at about 4.5 billion rupiah and monthly operating costs at roughly 2.6 billion rupiah. The figures show that frozen food growth is creating opportunities not only for food manufacturers but also for cold-storage operators, refrigerated transport providers and cold-chain technology companies.
Malaysia offers a different market profile because its consumer base is much smaller, but higher urbanization, income levels and modern retail infrastructure make frozen food relatively easy to distribute. The country is also expanding its frozen-food logistics infrastructure; in February 2025, Malaysia’s Department of Fisheries supported the launch of Ninja Cold, a nationwide frozen-food delivery service. The service was designed to help businesses expand their market reach through temperature-controlled transportation, illustrating how cold chain is increasingly becoming commercial infrastructure rather than merely a support function. With a population far smaller than Indonesia’s, Malaysia represents a smaller market in absolute terms but can provide opportunities for higher-value products and regional distribution.
The Philippines is another significant market because of its large population and expanding consumption of processed food. USDA data for 2025 estimated the Philippine population at 121 million, with 47% of residents under 24, a median age of 25 and an urbanization rate of about 48%. Retail food sales were projected to increase 5% in 2025, while the foodservice sector was expected to grow about 12%, supported by expanding restaurant networks and delivery services. For frozen food specifically, market estimates put the sector at around US$1.35 billion in 2025, with a projected CAGR of about 9.1% through 2035, faster than the estimated growth of Indonesia’s market between 2026 and 2031.
The Philippines’ growth also illustrates how frozen food is increasingly tied to convenience food and foodservice. Total packaged-food sales in the Philippines were estimated at US$19.11 billion in 2025, up from US$17.79 billion in 2024, and are projected to reach US$25.38 billion by 2029. Within that market, cooking ingredients and meals were estimated at US$3.26 billion in 2025, while processed meat, seafood and alternatives accounted for about US$2.90 billion. These figures point to a large underlying market for processed foods that can provide an entry point for frozen products, particularly ready-to-cook meals, processed meat and seafood.
Taken together, the numbers reveal three distinct Southeast Asian market profiles. Indonesia had an estimated frozen food market of US$3.38 billion in 2025 and a population of 284.67 million, while the Philippines had an estimated market of about US$1.35 billion and a population of 121 million; Malaysia has a considerably smaller consumer base but more developed modern retail and logistics infrastructure. Across ASEAN, the frozen food market is estimated at US$11.68 billion in 2025 and could more than double to US$27.42 billion by 2035. The differences in market size and consumer structure mean food companies cannot apply a single strategy across the region: Indonesia offers scale and distribution potential, Malaysia offers a smaller but relatively affluent consumer base, while the Philippines combines a young population with strong foodservice growth.
For food companies, the biggest opportunity in Indonesia ultimately lies in turning frozen products into an everyday consumption category rather than an occasional alternative. If the market estimated at US$3.61 billion in 2026 expands at a 6.78% CAGR, it could reach about US$5.01 billion by 2031, adding roughly US$1.4 billion in market value over five years. The ready-to-cook segment, which already accounts for 61.12% of the market, provides the volume base, while ready-to-eat products growing at a 7.34% CAGR create room for higher-value offerings. Behind that growth, the availability of freezers, cold storage, refrigerated transport and retail networks will determine how quickly frozen food can move beyond Indonesia’s largest cities into second- and third-tier markets.